
Xero Bank Reconciliation and Multi Currency Setup
A practical guide to connecting and reconciling Xero bank feeds correctly, then configuring multi-currency accounting — including realized vs. unrealized FX gains and losses — for businesses transacting internationally.
Quick Summary
- Bank Feed Connection: Xero connects directly to most banks via Yodlee/direct feeds, importing transactions automatically each business day.
- Reconciliation: matching imported bank statement lines against existing invoices, bills, and spend/receive money transactions — the core daily bookkeeping task in Xero.
- Bank Rules: automate repetitive categorization so recurring transactions (rent, subscriptions, bank fees) reconcile themselves correctly every time.
- Multi-Currency: a premium Xero feature that lets a business invoice, bill, and hold balances in currencies other than its base currency, with exchange rates updated automatically.
- FX Gains and Losses: multi-currency accounts must correctly distinguish realized (from settled transactions) from unrealized (from revaluing open balances) foreign exchange movements.
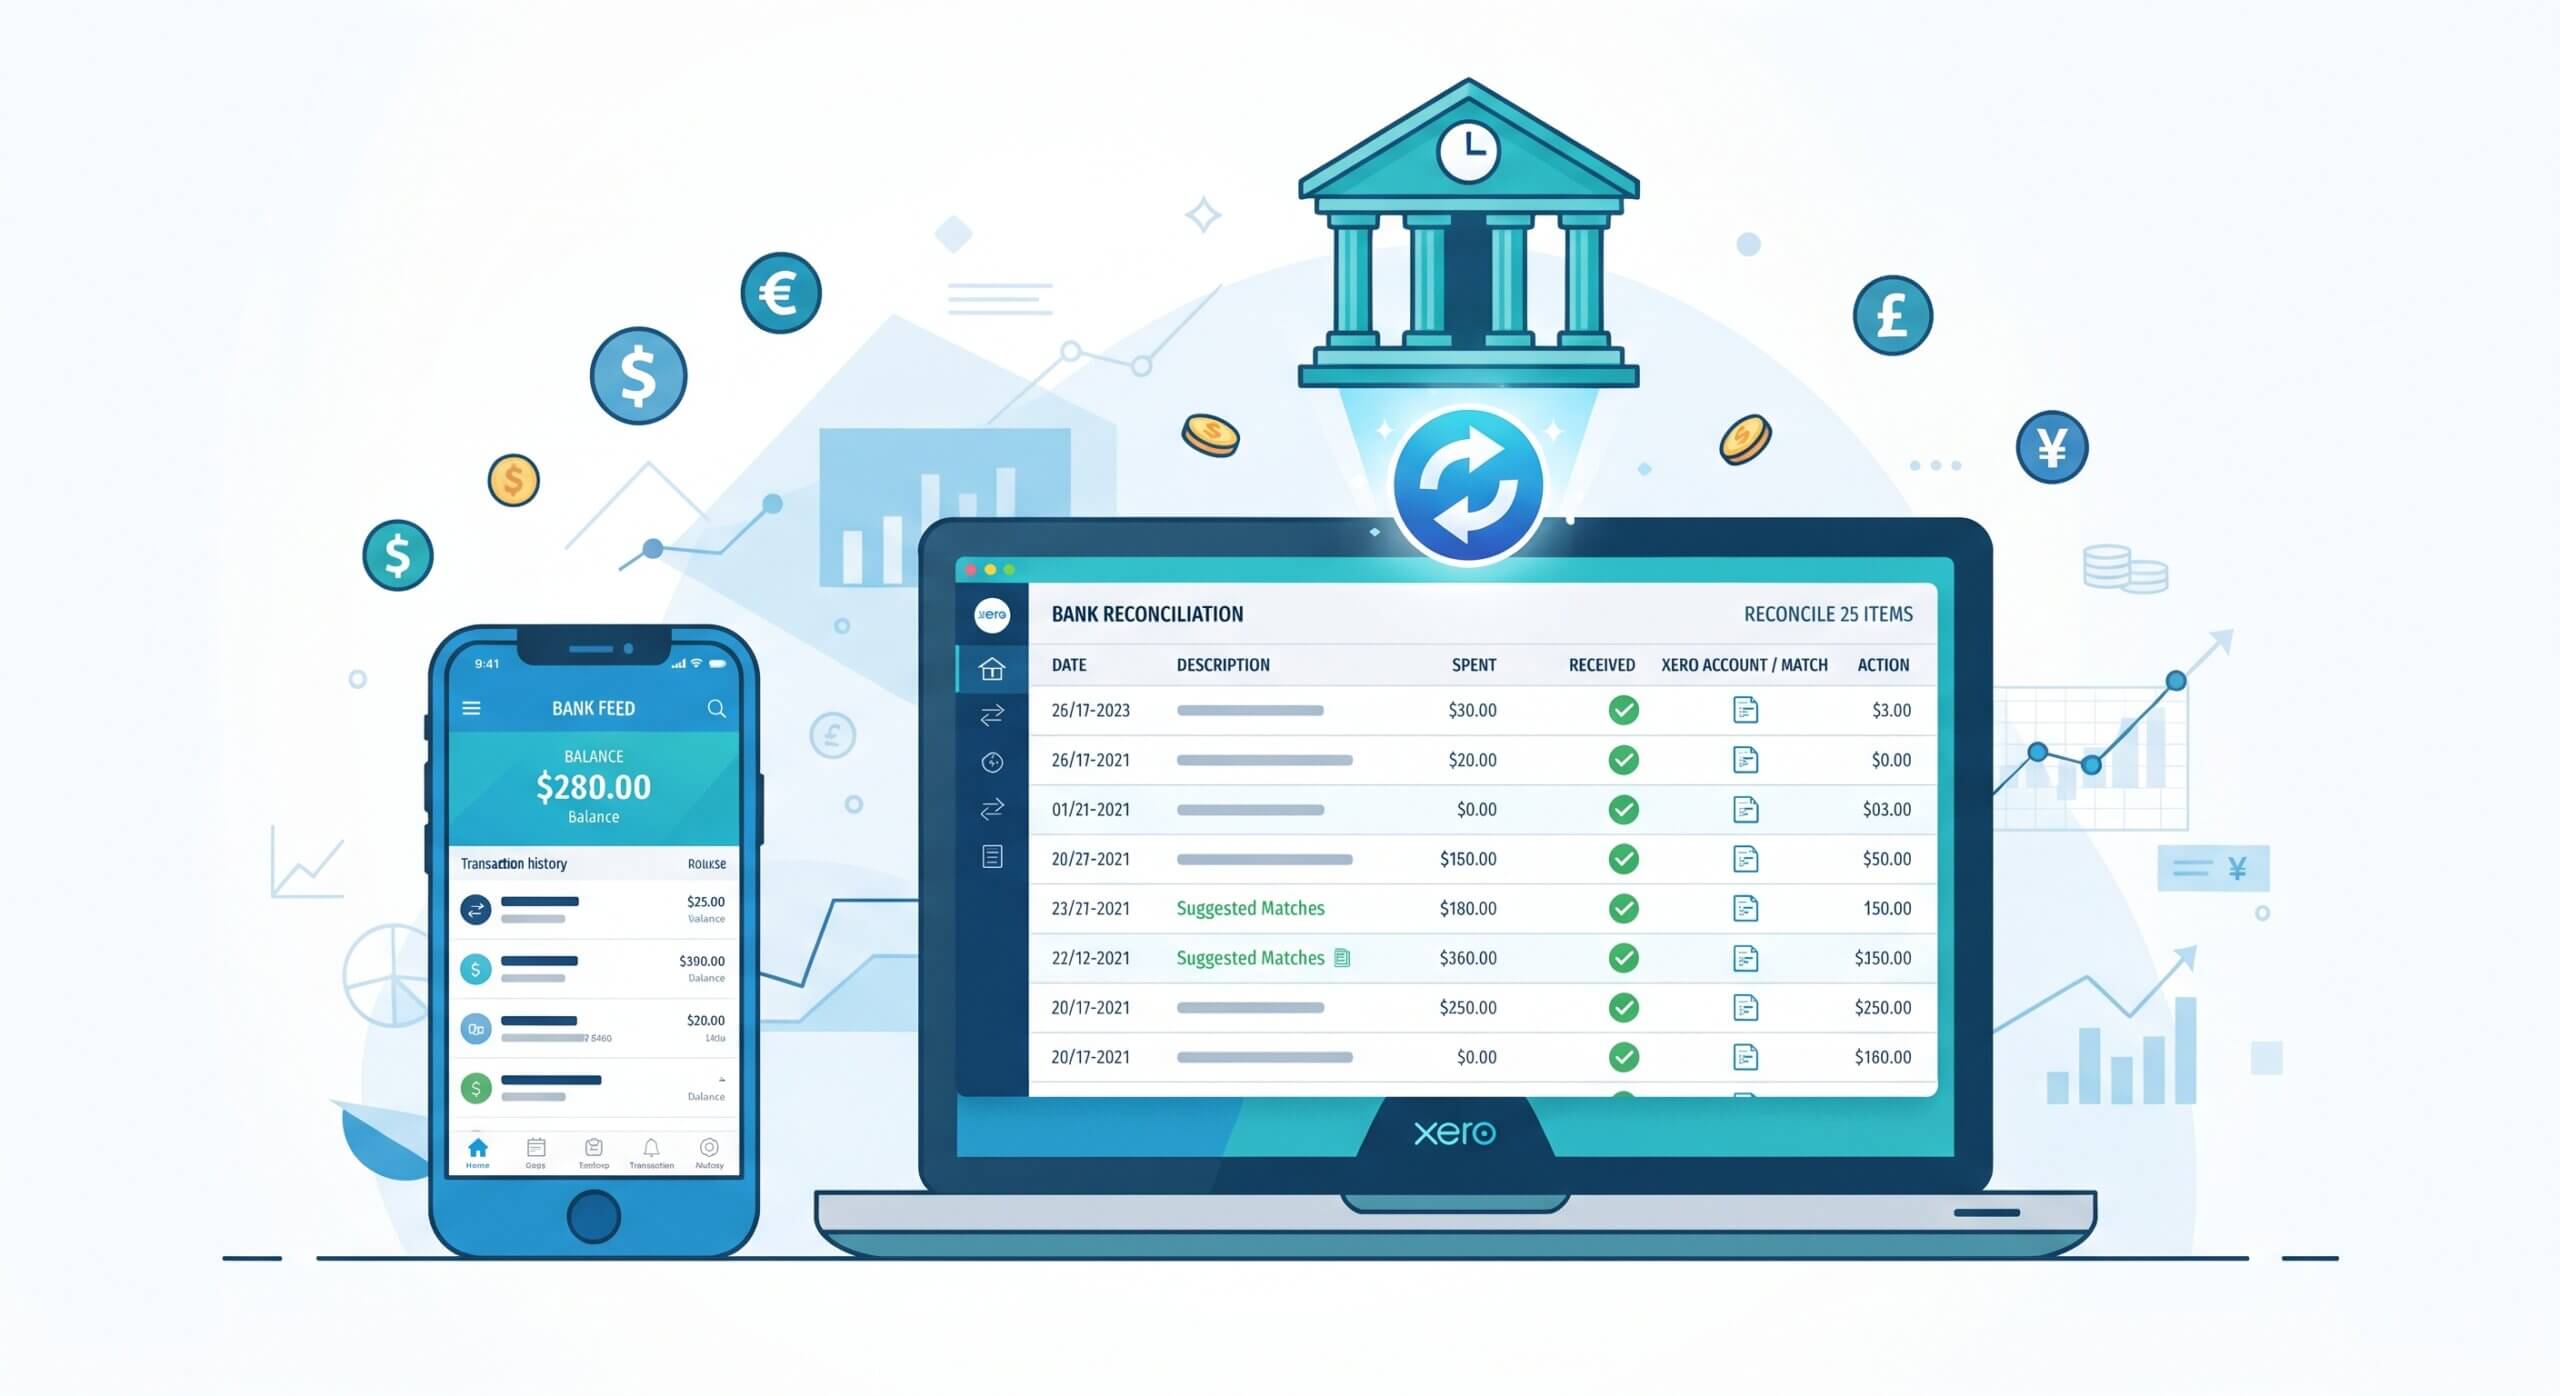
Scope & Objective
This guide covers the two capabilities that most determine whether a Xero file stays clean and audit-ready over time: correctly connecting and reconciling bank feeds, and correctly configuring multi-currency accounting for businesses that transact internationally. Both are foundational — a business that gets bank reconciliation wrong accumulates errors every single day, and a business that gets multi-currency setup wrong distorts its reported profit every time exchange rates move.
- Applies to: any Xero-subscribed business connecting a business bank account, and any business invoicing or paying suppliers in a currency other than its organization’s base currency (multi-currency requires the Established or Comprehensive Xero plan, depending on region).
- Core reconciliation principle: every imported bank statement line should be matched to a corresponding accounting transaction (an invoice payment, a bill payment, or a manually coded spend/receive money line) — never left sitting in the bank feed unreconciled.
- Core multi-currency principle: foreign-currency transactions are recorded at the exchange rate in effect on the transaction date, but outstanding foreign-currency balances must be revalued to the current rate at each reporting date, with the resulting movement recognized correctly as realized or unrealized.
- Out of scope: Xero payroll setup, inventory/tracked items, and third-party app integrations (e.g., point-of-sale connectors) are not covered here.
Connecting Bank Feeds in Xero
A bank feed is a direct, automated connection between a business bank account and its Xero organization, importing new transactions daily without any manual statement upload.
- Direct feeds: for banks with a direct partnership with Xero, transactions typically import automatically once the connection is authorized, usually within one business day of the transaction posting at the bank.
- Aggregator-based feeds: where no direct feed exists, Xero uses a third-party data aggregator (e.g., Yodlee) that securely retrieves transaction data using the account holder’s own online banking credentials, refreshed automatically on a regular schedule.
- Manual statement import: as a fallback when no automated feed is available, bank statements can be exported from online banking as a CSV, OFX, or QIF file and imported directly into the relevant bank account in Xero.
- Feed health monitoring: a feed that silently stops updating (a common cause of “my reconciliation doesn’t match the real bank balance”) is flagged on the Xero dashboard with a “feed issue” notice — this should be checked regularly, not only when a reconciliation discrepancy is discovered.

Reconciling Transactions and Bank Rules
Once transactions are flowing into Xero, reconciliation is the process of confirming that each one is correctly reflected in the accounts — the single most important recurring bookkeeping task in the system.
Matching occurs when an imported bank statement line lines up with a transaction already recorded in Xero (e.g., a customer’s payment against an existing invoice) — Xero suggests these matches automatically based on amount, date proximity, and contact history, and the user simply confirms them.
Creating occurs when no matching transaction exists yet — the user codes the bank line directly to an account (e.g., “Bank Fees,” “Office Supplies”), which both reconciles the line and creates the underlying accounting entry in a single step.
Getting the balance between these two right — matching wherever a transaction already exists, and creating (correctly coded) wherever it doesn’t — is what keeps the bank account balance in Xero equal to the real bank balance at all times.
Reconciling correctly:
- Reconcile frequently — daily or every few days — rather than in a large batch at month-end, since a small daily backlog is far easier to review accurately than weeks of accumulated transactions.
- Never “Discard” a bank line to make it disappear from the reconciliation screen without a genuine reason (e.g., a genuine duplicate feed entry) — a discarded line still happened at the bank and must be accounted for somewhere.
- Investigate any line Xero cannot suggest a match for rather than coding it to a generic account by default; an unexplained transaction is often the first sign of a billing error, a missed invoice, or a fraudulent charge.
- Run the Bank Reconciliation Summary report regularly to confirm the Xero-calculated balance genuinely ties out to the bank statement balance, not just to assume reconciling individual lines is sufficient on its own.
Bank Rules for automation:
- A bank rule automatically codes future transactions that match a defined condition (e.g., payee contains “AWS,” amount is fixed, reference matches a pattern) to a specified account, tax rate, and contact.
- Best suited to: genuinely recurring, predictable transactions — rent, loan repayments, subscription charges, bank fees — where the coding decision never actually changes.
- Review periodically rather than “set and forget” — a rule that was correct when created can silently miscode transactions if a vendor’s payment reference format changes.
- Avoid over-broad conditions (e.g., matching on amount alone) that could accidentally auto-code an unrelated transaction that happens to share the same value.
Multi-Currency Setup and Revaluation
Multi-currency accounting lets a business hold bank accounts, raise invoices, and receive bills in currencies other than its Xero organization’s base (reporting) currency, with Xero converting balances automatically for reporting purposes.
- Enabling multi-currency: available on eligible Xero plans; once enabled it cannot be disabled, so it should only be turned on for organizations genuinely transacting internationally.
- Exchange rates: Xero automatically retrieves daily exchange rates from an external rate provider (XE.com) for transaction-date conversion, though a manual exchange rate can be entered on an individual transaction when a contractually agreed rate applies instead.
- Foreign-currency bank accounts: a bank account can be added in a currency other than the organization’s base currency, holding its own balance in that currency while still reporting a base-currency equivalent throughout Xero.
- Currency revaluation: outstanding foreign-currency balances (unpaid invoices, unpaid bills, foreign bank account balances) are converted to base currency at the transaction-date rate when first recorded, but their base-currency value changes as exchange rates move over time — Xero’s Revaluation report recalculates these balances at a current rate as at a chosen date, most commonly used at month-end or year-end close.
Handling Realized and Unrealized FX Gains and Losses
Exchange rate movements between when a foreign-currency transaction is recorded and when it is actually settled (or revalued) create gains or losses that must be classified correctly.
- Realized gain or loss: arises when a foreign-currency invoice or bill is actually paid, and the exchange rate on the payment date differs from the rate on the original transaction date — this is a genuine cash-flow effect that has actually occurred.
- Unrealized gain or loss: arises purely from revaluing a still-open foreign-currency balance (an unpaid invoice or bill, or a foreign bank account) to a current exchange rate at a reporting date — no cash has actually changed hands, so this reflects only a paper/reporting adjustment as of that date.
- Xero automates both calculations once multi-currency is enabled — realized gains/losses post automatically at the moment a foreign-currency transaction is paid, and unrealized gains/losses post when the Revaluation report is run and its adjusting journal is applied.
- Reporting placement: both realized and unrealized FX gains/losses typically post to their own dedicated accounts in the chart of accounts (commonly under Other Income/Other Expense), keeping them visibly separate from operating revenue and expenses rather than blended into regular trading results.
Reviewing Reconciliation and Multi-Currency Reports
Beyond the day-to-day reconciliation screen, a handful of standard Xero reports give a periodic sanity check that the bank accounts and foreign-currency balances are genuinely correct, not just individually reconciled transaction by transaction.
- Bank Reconciliation Summary: compares the Xero-calculated balance for each bank account against the actual statement balance as at a chosen date, immediately surfacing any gap that individual line-by-line reconciliation may have missed.
- Bank Statement report: shows every imported bank line alongside its reconciliation status, useful for spotting transactions that were imported but never actually reconciled.
- Foreign Currency Gains and Losses report: breaks down realized and unrealized movements by account and period, making it straightforward to confirm both figures are flowing to the correct, separate accounts described above.
- Running these reports at least monthly, rather than only when a problem is suspected, catches small discrepancies while they are still easy to trace back to a single cause.

Common Xero Bank Feed and Multi-Currency Mistakes
- Letting bank feed issues go unnoticed for an extended period, causing reconciliation to silently fall out of sync with the real bank balance until a large, hard-to-untangle backlog builds up.
- Discarding bank lines instead of properly coding or matching them, effectively hiding real transactions from the accounting records rather than accounting for them.
- Creating overly broad bank rules that miscode transactions sharing a coincidental amount or partial reference match with the rule’s intended target.
- Forgetting to run currency revaluation at period-end, leaving foreign-currency balances reported at stale transaction-date rates rather than current rates on the balance sheet.
- Blending realized and unrealized FX movements into a single account, obscuring how much of a reported gain or loss reflects actual cash impact versus a still-open paper position.
- Manually overriding an exchange rate on a routine transaction without a genuine contractual basis for doing so, which quietly distorts both the transaction’s value and any later revaluation calculated from it.
Need Help Setting Up Xero for Your Business?
Need expert help configuring bank feeds, reconciliation workflows, or multi-currency accounting in Xero? Contact our Accounting & Bookkeeping team today.