
🌐 Global IFRS
IFRS 9 Expected Credit Loss Impairment Model
A practical guide to the forward-looking Expected Credit Loss (ECL) framework under IFRS 9 — the three-stage general approach, the simplified approach for trade receivables, and how to build defensible, forward-looking provision estimates.
Quick Summary
- Forward-looking model — IFRS 9 replaced IAS 39’s “incurred loss” model with an Expected Credit Loss (ECL) model that recognizes impairment before a default event actually occurs.
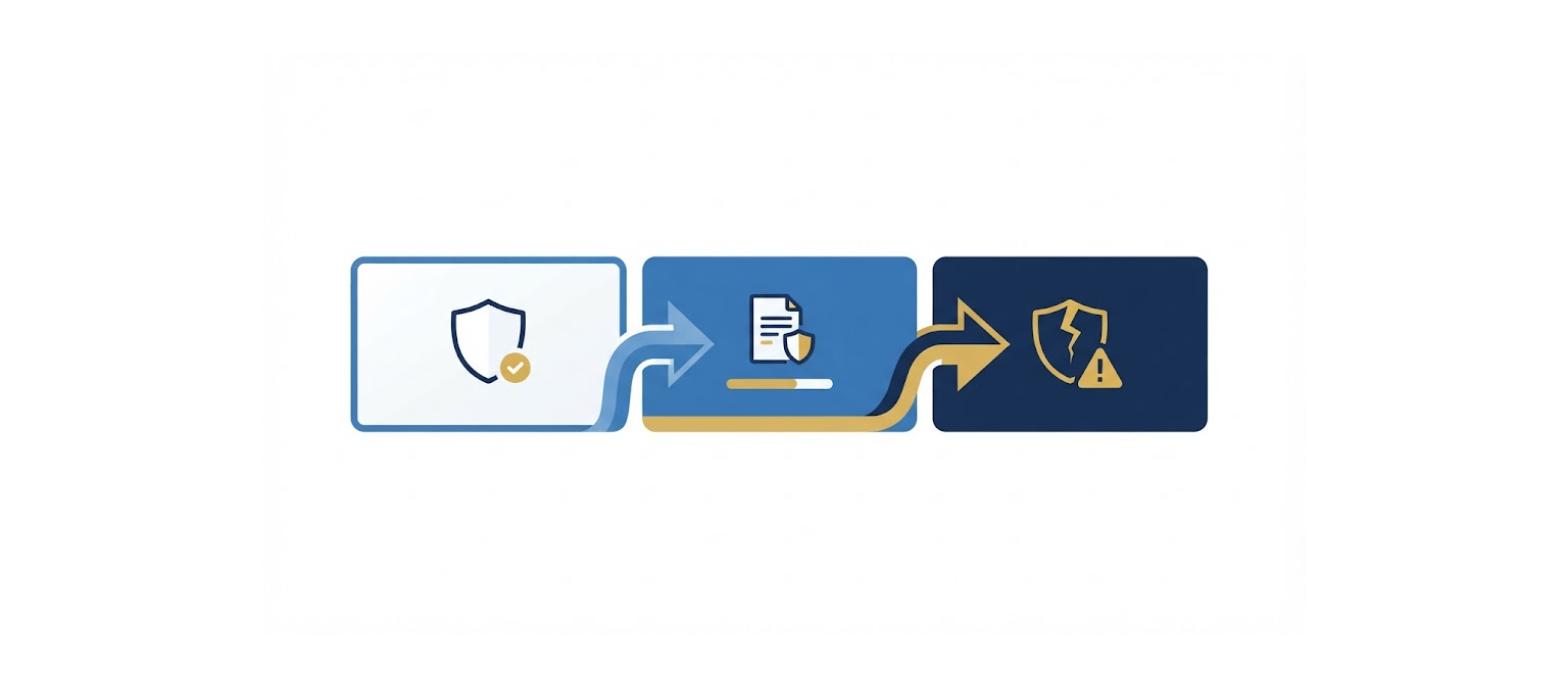
- Three stages — financial assets move between Stage 1 (12-month ECL), Stage 2 (lifetime ECL, no default yet), and Stage 3 (lifetime ECL, credit-impaired), driven by changes in credit risk since initial recognition.
- Simplified approach — trade receivables, contract assets, and lease receivables can use a simplified model that recognizes lifetime ECL from day one, typically via a provision matrix.
- Forward-looking inputs required — historical loss rates must be adjusted for current conditions and reasonable, supportable forecasts of future economic conditions.
Scope & Objective
The impairment requirements in IFRS 9 apply to financial assets measured at amortized cost, debt instruments measured at fair value through other comprehensive income (FVOCI), lease receivables, contract assets within the scope of IFRS 15, loan commitments not measured at fair value through profit or loss, and financial guarantee contracts not measured at fair value through profit or loss.
The objective of the ECL model is to ensure entities recognize impairment allowances that reflect an unbiased, probability-weighted estimate of credit losses, incorporating the time value of money and reasonable, supportable information about past events, current conditions, and forecasts of future economic conditions — rather than waiting for objective evidence of impairment to arise, as was required under the old incurred-loss model in IAS 39.

The Shift from Incurred Loss to Expected Loss
Under IAS 39’s incurred-loss model, an entity could only recognize an impairment loss once there was objective evidence of a loss event — such as a missed payment, covenant breach, or bankruptcy filing. Critics, particularly following the 2008 global financial crisis, argued this approach recognized credit losses “too little, too late,” since deteriorating credit quality was often visible well before an actual default occurred.
IFRS 9 addresses this by requiring entities to recognize an allowance for expected credit losses at initial recognition of a financial asset, and to update that estimate at each reporting date based on changes in credit risk. This means every financial asset within scope carries an ECL allowance from day one — even a newly originated loan that is fully performing.
The Three-Stage General Approach
The general approach classifies financial instruments into one of three stages based on the change in credit risk since initial recognition. Movement between stages is not a one-way ratchet — an asset that has migrated to Stage 2 or Stage 3 can move back to a lower stage if its credit risk subsequently improves.
| Stage | Trigger | ECL Basis | Interest Recognition |
|---|---|---|---|
| Stage 1 — Performing | No significant increase in credit risk since initial recognition | 12-month ECL | Effective interest on gross carrying amount |
| Stage 2 — Underperforming | Significant increase in credit risk since initial recognition, but not yet credit-impaired | Lifetime ECL | Effective interest on gross carrying amount |
| Stage 3 — Credit-impaired | Objective evidence of impairment (default, missed payments, restructuring, bankruptcy) | Lifetime ECL | Effective interest on net carrying amount (gross less allowance) |
Bidirectional migration: Staging is reassessed at every reporting date, not just at origination. An asset can move from Stage 2 back to Stage 1 if the significant increase in credit risk that caused the transfer no longer exists — entities need a documented policy for both downgrade and cure/upgrade triggers, not just deterioration triggers.
A financial asset is considered credit-impaired when one or more events have occurred that have a detrimental impact on the estimated future cash flows of that asset. Once management concludes there is no reasonable expectation of recovering a financial asset in its entirety or a portion of it, the gross carrying amount should be written off — directly or against the related allowance — even if enforcement activity to recover the amounts owed continues.
Measuring Expected Credit Losses: PD, LGD, and EAD
ECL is not a single number pulled from a table — it is the output of a probability-weighted calculation built from three core credit risk parameters, discounted back to the reporting date at the instrument’s effective interest rate.
- Probability of Default (PD) — the likelihood that a borrower will default within a given time horizon (12 months for Stage 1, or the remaining lifetime of the instrument for Stage 2 and Stage 3).
- Loss Given Default (LGD) — the proportion of the exposure the entity expects to lose if a default occurs, net of expected recoveries such as collateral realization, expressed as a percentage of exposure at default.
- Exposure at Default (EAD) — the expected gross carrying amount of the exposure at the point of default, including drawn balances and, where relevant, an estimate of further drawdowns on undrawn commitments.
For Stage 1 assets, entities apply a 12-month ECL — the portion of lifetime expected credit losses that would result from default events possible within 12 months of the reporting date. For Stage 2 and Stage 3 assets, entities must estimate lifetime ECL — expected credit losses from all possible default events over the expected life of the instrument. Discounting uses the instrument’s original effective interest rate, so the time value of money is embedded directly in the allowance.
The Simplified Approach for Trade Receivables
Recognizing that a full three-stage assessment is impractical for high-volume, short-duration receivables, IFRS 9 permits — and in some cases requires — a simplified approach for trade receivables and contract assets that do not contain a significant financing component. Under this approach, entities recognize lifetime ECL for these assets from initial recognition, with no need to track staging or monitor for significant increases in credit risk.
The most common practical tool for the simplified approach is a provision matrix, which groups receivables into ageing buckets and applies a historical loss rate to each bucket, adjusted for current conditions and forward-looking factors:
| Ageing Bucket | Historical Loss Rate | Forward-Looking Adjustment | Applied Provision Rate |
|---|---|---|---|
| Current (not past due) | 0.3% | +0.1% | 0.4% |
| 1–30 days past due | 1.5% | +0.3% | 1.8% |
| 31–60 days past due | 6.0% | +1.0% | 7.0% |
| 61–90 days past due | 18.0% | +2.0% | 20.0% |
| Over 90 days past due | 45.0% | +5.0% | 50.0% |
Receivables from customers sharing similar credit risk characteristics — such as geographic region, product type, customer type, or credit rating — should be grouped together so that the loss rate applied is a reasonable proxy for the group’s actual risk profile.
Purchased or Originated Credit-Impaired (POCI) Assets
Financial assets that are already credit-impaired at the point of initial recognition — for example, a loan acquired at a deep discount because the borrower is already in financial difficulty — follow a different path through the ECL model, known as the POCI category.
- POCI assets are never classified into Stage 1, 2, or 3 in the same way as other financial assets — they carry a lifetime ECL allowance from initial recognition, since they were already impaired when acquired.
- Interest income is calculated by applying a credit-adjusted effective interest rate to the amortized cost of the asset, which already factors in expected credit losses at initial recognition.
- At each subsequent reporting date, only the cumulative changes in lifetime expected credit losses since initial recognition are recognized as an impairment gain or loss — not the full lifetime ECL balance each period.
Correctly identifying POCI assets at acquisition is important: misclassifying a credit-impaired acquisition as a normal Stage 1 or Stage 2 asset would materially understate the effective interest rate calculation and distort both interest income and impairment charges over the life of the asset.
Incorporating Forward-Looking Information
A defining feature of IFRS 9’s impairment model is the explicit requirement to incorporate reasonable and supportable forward-looking information that is available without undue cost or effort, rather than relying solely on historical loss experience. Entities typically achieve this by:
- Identifying macroeconomic variables that correlate with historical credit losses for a given portfolio — such as GDP growth, unemployment rates, interest rates, commodity prices, or property price indices.
- Building multiple economic scenarios (for example, a base case, an upside case, and a downside case) and assigning probability weightings to each.
- Adjusting historical loss rates or model outputs for the projected path of these variables under each scenario, then probability-weighting the results into a single ECL estimate.
- Reassessing scenario weightings and macroeconomic assumptions at each reporting date, since economic conditions and outlooks change over time.
This forward-looking overlay is often the most judgmental part of the ECL calculation, and is an area of particular focus for auditors and regulators — the assumptions used, and the sensitivity of the ECL estimate to them, typically require detailed disclosure under IFRS 7.
Common Mistakes in Applying the ECL Model
- Treating 12-month ECL as a cash-flow forecast horizon rather than a probability-weighted concept — 12-month ECL is the portion of lifetime losses arising from default events possible within 12 months, not simply losses expected to be realized in cash within the next year.
- Using purely historical loss rates with no forward-looking adjustment — a provision matrix built only on historical data, without any overlay for current or forecast conditions, does not meet the standard’s requirements.
- Failing to reassess staging at each reporting date — staging is not a one-time classification at origination; every reporting period requires a fresh assessment of whether credit risk has increased significantly.
- Ignoring collateral and credit enhancements inconsistently — LGD estimates should reflect the specific collateral and enhancements attached to an exposure, not a blanket assumption applied across dissimilar exposures.
- Delaying write-offs pending full legal exhaustion — a write-off should occur once there is no reasonable expectation of recovery, which can precede the completion of formal legal or collection processes.
Need Help Building an IFRS 9-Compliant ECL Model?
SABIO Consultancy’s financial advisory and compliance team helps organizations design defensible ECL methodologies, build provision matrices, and prepare audit-ready IFRS 9 impairment disclosures.