
When a third party is involved in delivering goods or services, IFRS 15 requires an entity to determine whether it is the principal or the agent in the arrangement — a decision that directly changes whether revenue is reported gross or net.
- The core test is control, not legal title or invoicing
- Four key indicators: fulfilment responsibility, inventory risk, price discretion, credit risk
- How the test applies to marketplaces, ticketing, and travel agents
- A worked example of an online marketplace commission
Part 1: Fundamentals & the Five-Step Model · Part 2: Worked Examples · Part 3: Variable Consideration · Part 4: Contract Modifications · Part 5: Principal vs. Agent · Part 6: Licensing & Royalties
Why Principal vs. Agent Matters
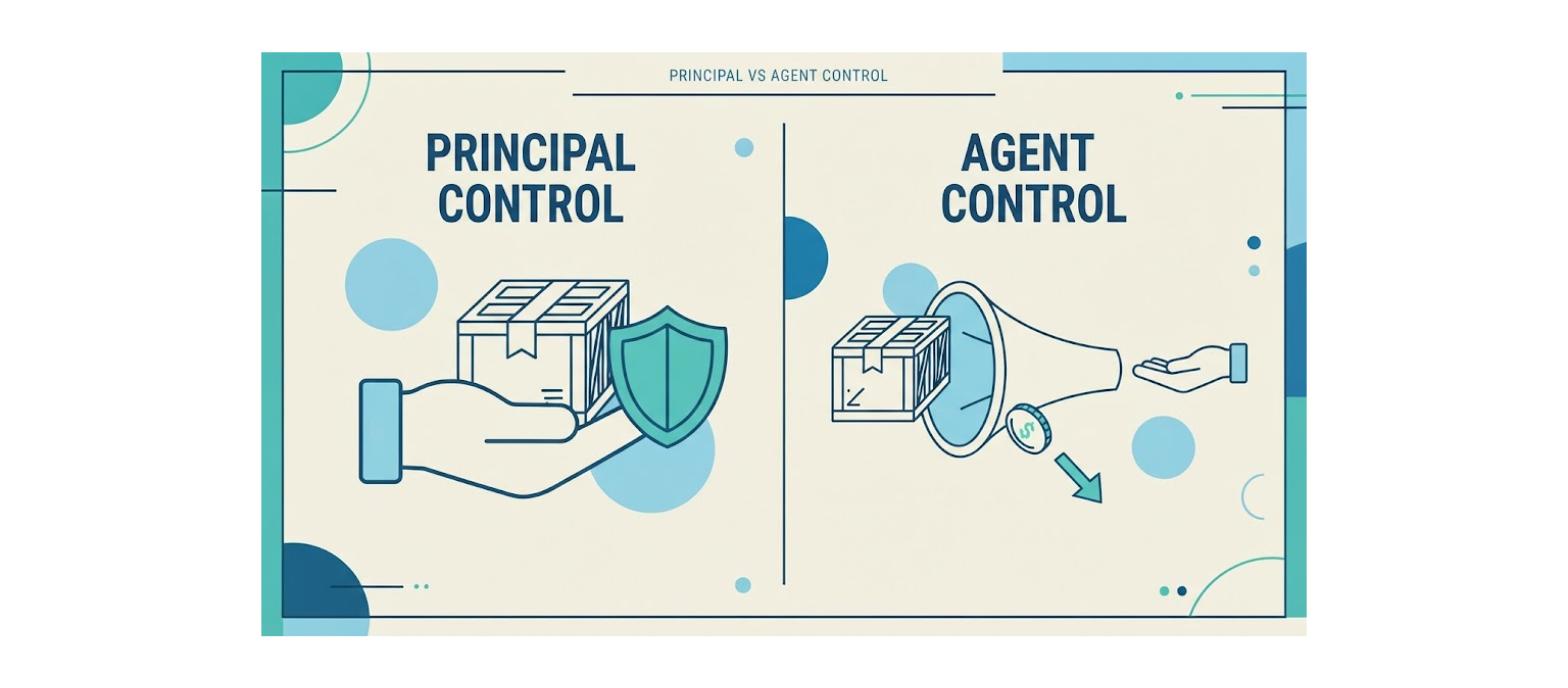
When another party is involved in providing goods or services to a customer, an entity must determine whether its own promise is to provide the goods or services itself (acting as principal) or to arrange for another party to provide them (acting as agent). The distinction changes how much revenue is recognised: a principal recognises revenue at the gross amount of consideration, while an agent recognises revenue at the net amount it retains — typically a fee or commission. Getting this wrong can materially misstate reported revenue even though profit is unaffected.
The Core Control Principle
The determining question is not who has legal title, or who invoices the customer, but who controls the specified good or service before it is transferred to the customer. An entity is a principal if it controls the good or service before transferring it. An entity is an agent if its role is to arrange for another party to provide the good or service, without ever controlling it.
Indicators You Are the Principal
| Indicator | Principal | Agent |
|---|---|---|
| Primary responsibility for fulfilment | Entity is primarily responsible for fulfilling the promise, including acceptability of the good or service | Responsibility rests with the other party |
| Inventory risk | Entity has inventory risk before or after the customer order, during shipping, or on return | No inventory risk taken on |
| Price discretion | Entity has discretion in establishing the price the customer pays | Price is set by the other party; entity earns a fixed or percentage fee |
| Exposure to credit risk | Entity bears the credit risk of collecting from the customer | Credit risk sits with the other party |
Common Scenarios: Marketplaces, Ticketing, Travel Agents
Online marketplaces that never take title to inventory, host the seller’s listing, and simply process payment for a commission are typically agents — they recognise only the commission as revenue. Ticketing platforms that resell tickets they have purchased and hold inventory risk on are typically principals for the face value of the ticket. Travel agents booking flights and hotels on behalf of a traveller, without ever controlling the accommodation or flight seat itself, are typically agents earning a booking fee or commission.
Worked Example: Online Marketplace Commission
An online marketplace lists third-party sellers’ products. A customer buys a $500 product from a seller through the platform. The platform collects the full $500 from the customer, remits $450 to the seller, and retains $50 as its commission. The platform never takes title to the product, does not set the price (the seller does), bears no inventory risk, and is not responsible for the acceptability of the product — the seller is.
Analysis: the platform does not control the product before it is transferred to the customer. It is an agent. Revenue recognised by the platform is $50 (the commission), not the $500 gross transaction value. The seller recognises $450 as its own revenue for the sale of the product (assuming the seller is the principal).
Common Mistakes
- Assuming that because an entity invoices the customer for the full amount, it must recognise revenue gross.
- Focusing only on legal title rather than control, especially in arrangements where title passes momentarily but no real control is exercised.
- Applying a blanket “we are always the principal” or “we are always the agent” policy across an entire platform without assessing each class of transaction.
- Ignoring inventory risk and price-setting discretion, which are often the strongest indicators of control in practice.
Not Sure If You Are the Principal or the Agent?
We can review your marketplace or platform arrangements against the IFRS 15 control test.