
The Accounting Cycle Explained: From Transactions to Financial Statements
A step-by-step walkthrough of the accounting cycle, from analyzing a single transaction through to the final financial statements.
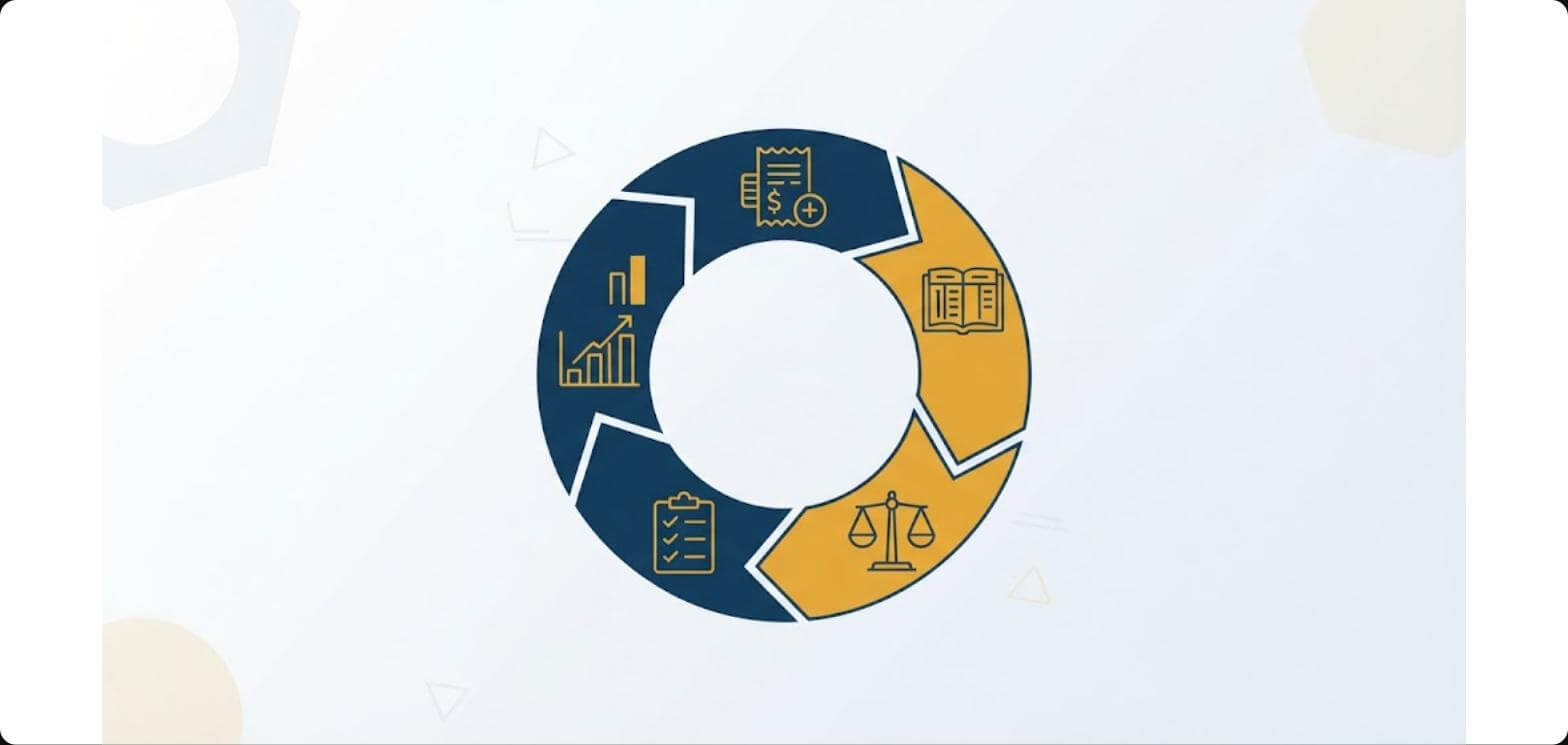
- The accounting cycle is the repeating sequence of steps a business follows every reporting period to turn raw transactions into a finished set of financial statements — the same five-step logic underlies virtually every accounting system, manual or automated.
- Five core steps: analyze and record each transaction, post it to the general ledger, prepare a trial balance and make adjusting entries, close the temporary accounts, and produce the final financial statements.
- Double-entry is the backbone: every transaction affects at least two accounts, and total debits must always equal total credits at every stage of the cycle — this single rule is what makes the trial balance a meaningful check.
- Why it matters: understanding the cycle as a whole — not just individual journal entries — is what lets a bookkeeper or accountant trace a number on the financial statements all the way back to the original transaction, and vice versa.
Scope & Objective
This guide walks through the full accounting cycle from a single transaction being recorded through to that transaction’s effect appearing on the final financial statements. It’s written as a foundational reference — the sequence and logic apply whether the business uses a fully manual ledger, a spreadsheet, or accounting software like Xero or QuickBooks Online (where most of these steps happen automatically in the background, but the underlying logic is identical).
- Applies to: any business using double-entry bookkeeping, regardless of size, industry, or accounting software.
- Out of scope: the specific chart-of-accounts design choices, industry-specific adjusting entries, and jurisdiction-specific disclosure requirements, which are covered in their own dedicated guides.
A short worked-example walkthrough of a full accounting cycle — from journal entry to financial statements — is a useful companion to this guide if you prefer to see the sequence applied to a single running example rather than read it in the abstract. Ask your SABIO advisor for a recorded walkthrough tailored to your own chart of accounts, or work through the five steps below using one of your own recent transactions as a live example.

Step 1: Analyzing and Recording Transactions
The cycle begins the moment a business event occurs — a sale, a purchase, a payment, a receipt — and is supported by a source document: an invoice, a receipt, a bank statement line, a signed contract. The first task is to analyze that source document and determine which accounts it affects and by how much.
- Identify the accounts involved. Every transaction touches at least two accounts. A cash sale, for example, increases Cash (an asset) and increases Sales Revenue (income).
- Apply the rules of debit and credit. Assets and expenses increase with a debit and decrease with a credit; liabilities, equity, and income increase with a credit and decrease with a debit. This is the mechanical rule that keeps the accounting equation — Assets = Liabilities + Equity — in balance after every single entry.
- Record the journal entry. The transaction is entered in the general journal (or its software equivalent) in chronological order, showing the date, the accounts debited and credited, the amounts, and a brief narration describing the transaction.
Worked example: a business pays $2,000 cash for office rent. The journal entry debits Rent Expense $2,000 and credits Cash $2,000 — an expense increasing (debit) and an asset decreasing (credit), with the two sides equal.
Step 2: Posting to the General Ledger
Once transactions are recorded as journal entries, each entry is posted — copied — into the general ledger, where entries are reorganized by account rather than by date. Each account (Cash, Accounts Receivable, Rent Expense, Sales Revenue, and so on) has its own ledger page or record, accumulating every debit and credit that has ever been posted to it.
- Purpose of posting: the journal shows transactions in the order they happened; the ledger shows the running effect on each individual account, which is what’s actually needed to know an account’s current balance.
- Running balance: after each posting, the ledger account’s balance is recalculated — for an asset or expense account, debits minus credits; for a liability, equity, or income account, credits minus debits.
- In modern accounting software, this step happens automatically the instant a transaction is entered — but the underlying ledger structure, and the ability to drill down from a financial statement line into the individual postings behind it, is exactly this same logic.
Step 3: Unadjusted Trial Balance and Adjusting Entries
At the end of the reporting period, every ledger account’s balance is listed in a single report — the trial balance — with debit balances in one column and credit balances in another. If every transaction was recorded and posted correctly, total debits equal total credits.
- The unadjusted trial balance is a straight listing of ledger balances before any period-end adjustments — it catches basic recording or posting errors (a debit posted without a matching credit, a transposed number) but does not by itself guarantee the accounts are complete or accurate.
- Adjusting entries are then made to bring the accounts up to date on an accrual basis before the trial balance is finalized. Common categories include:
- Accrued expenses — costs incurred but not yet paid or recorded, such as unpaid utility bills or wages earned but not yet paid at period-end.
- Accrued revenue — revenue earned but not yet invoiced or received.
- Prepayments — expenses paid in advance (like a full year’s insurance premium) that must be spread over the periods they actually cover, and revenue received in advance that hasn’t yet been earned.
- Depreciation — allocating the cost of a fixed asset over its useful life.
- Bad debt or inventory adjustments — writing down receivables unlikely to be collected, or reconciling recorded inventory to a physical count.
After adjusting entries are posted, an adjusted trial balance is prepared — the version that actually feeds into the financial statements.
Step 4: Closing Entries
Closing entries are made only at the end of a full accounting period (not every month, in businesses that close annually), and their purpose is narrow but important: to reset the temporary accounts to zero so the next period starts fresh, while transferring their net effect into a permanent equity account.
- Temporary accounts — all income and expense accounts, plus any dividends or drawings account — are “temporary” because they measure activity for a single period only and must not carry a balance into the next one.
- Permanent accounts — assets, liabilities, and equity accounts — carry their balances forward from one period to the next without being closed.
- The closing sequence: income and expense account balances are transferred into a summary account (often called Income Summary), which nets to the period’s profit or loss; that net figure is then transferred into Retained Earnings (or the equivalent equity account); finally, any drawings or dividends account is also closed against equity.
- After closing entries are posted, a post-closing trial balance is prepared, containing only permanent (balance sheet) accounts — every income and expense account should show a zero balance, confirming the close was done correctly.
Step 5: Preparing the Final Financial Statements
The adjusted trial balance (before closing) is what’s actually used to prepare the period’s financial statements — closing entries happen afterward, purely to reset the ledger for the next period, and don’t change the figures already reported.
- Income Statement — built first, from the adjusted income and expense account balances, arriving at net profit or loss for the period.
- Statement of Changes in Equity — brings in that net profit or loss figure, along with any capital contributions or drawings/dividends, to roll forward the equity balance from the start to the end of the period.
- Balance Sheet — built from the adjusted asset, liability, and equity balances (including the updated equity figure from the statement above), as of the last day of the period.
- Cash Flow Statement — typically prepared last, since it draws on both the income statement and the comparison of two balance sheet dates to explain the movement in cash over the period.
Once these four statements are complete and internally consistent — net profit flows correctly into equity, and the balance sheet actually balances — the accounting cycle for that period is finished, and the next period begins again at Step 1.

Common Accounting Cycle Mistakes
- Skipping the unadjusted trial balance and jumping straight to adjustments — this removes the basic checkpoint that catches recording and posting errors before they compound into the adjusting entries.
- Forgetting one or more adjusting entries, especially accruals for expenses that haven’t been invoiced yet, which understates liabilities and overstates profit for the period.
- Closing temporary accounts before finalizing the financial statements, rather than after — the statements must be drawn from the adjusted trial balance, not from a ledger that’s already been closed.
- Treating the cash flow statement as a starting point instead of the last statement prepared — it depends on figures from the income statement and two balance sheet dates that must already be finalized.
- Not reconciling the post-closing trial balance — skipping this final check means an incomplete or incorrect close can go unnoticed until it distorts the following period’s opening balances.
Need Help Closing the Books Correctly Each Period?
Our team can help set up your chart of accounts, review your close process, and make sure your financial statements are accurate and audit-ready.